Retirement Income · Life Insurance · Long-Term Care · Disability
Protection for today. Confidence for what comes next.
Independent life insurance and retirement income guidance from Sean Browning, RICP® — helping Colorado families protect the people who depend on them and create reliable income for the years ahead.
No cost · No obligation · No pressure
The Browning Two-Column Review
Every retirement income decision comes down to one question: what is actually guaranteed, and what is only projected? Most people never get a clear answer to that.
We show you both columns side by side, explain the assumptions behind the non-guaranteed one out loud, and name the trade-offs — surrender charges, caps, limits on access to your money — before anything is signed.
If a product doesn’t fit what you’re trying to do, we’ll tell you that too.
RICP®
Retirement Income Certified Professional, The American College of Financial Services
Since 2015
Serving families across Colorado and surrounding states from our Longmont office
Independent
Not tied to one carrier — we compare contracts across the companies we represent
★★★★★ 58 Google Reviews
See what clients say about Browning Insurance Agency →
This may be worth a conversation if…
You’re protecting a family, building a business, approaching retirement, or simply trying to understand what you already own:
- You have people depending on your income and aren’t sure you have enough life insurance.
- You recently married, had a child, bought a home, or started a business.
- You have a life insurance policy you don’t fully understand or haven’t reviewed in years.
- You’re within 5–10 years of retirement and aren’t sure how savings become dependable income.
- You’re concerned about a market decline, long-term care, or what happens financially if your spouse dies first.
Choose where to start
Life Insurance Planning
Protect the people and obligations that depend on you—from income replacement and mortgage protection to business needs, permanent coverage, and legacy planning.
Retirement Income Planning
Turn savings into dependable income, plan for a surviving spouse, evaluate annuities, and prepare for long-term-care costs without losing sight of liquidity and trade-offs.
Four questions life and retirement planning should answer
The right answer depends on who relies on you today, what you already have, what you still need, and how much certainty you want for the future.
How much life insurance does my family actually need?
We look at income replacement, debts, mortgage obligations, education goals, existing coverage, and how long the people you support would need help. The goal is appropriate protection—not simply the largest policy.
What happens financially if I die first?
Life insurance can replace lost income, protect a surviving spouse, fund business or estate needs, and create a deliberate legacy. We compare term and permanent options and explain what is guaranteed and what is not.
What if one of us needs long-term care?
Long-term care is the expense most likely to undo a retirement plan. We walk through what coverage costs now, what it covers later, and what happens if you never use it.
How do I turn savings into a paycheck?
Annuities can convert a portion of savings into payments that continue for life. We compare contracts from the carriers we represent, show you what’s guaranteed versus what isn’t, and explain the trade-offs—including what you give up in liquidity.
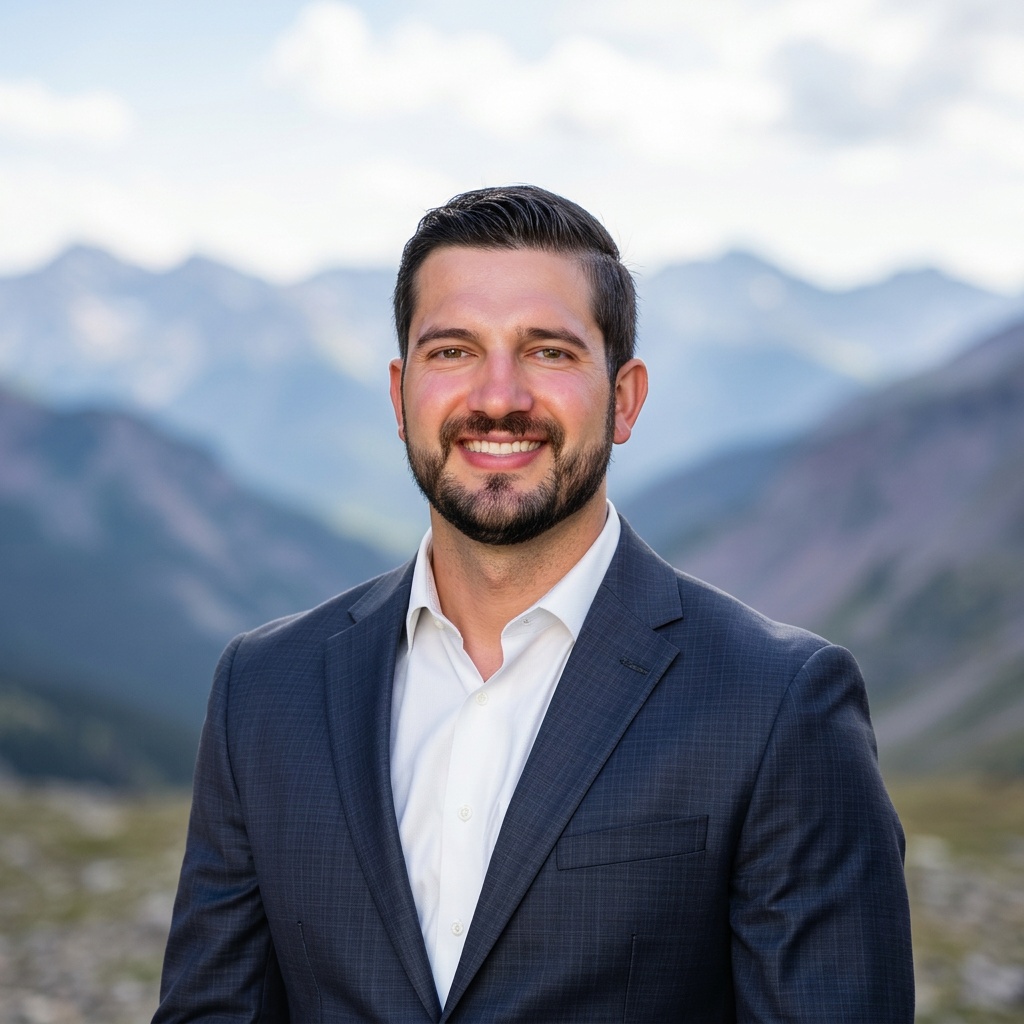
Sean Browning, RICP®
Sean has advised Colorado families on insurance since 2015. Over the last several years his work has shifted toward the questions that come up at the end of a working life — how savings become income, what happens to a surviving spouse, and what care costs when it’s needed.
He earned the Retirement Income Certified Professional designation to do that work properly rather than casually. It’s a credential built around retirement income specifically: sequence-of-returns risk, Social Security and pension timing, drawdown strategy, and where insurance products fit among them.
He works alongside Emily Browning, who manages the agency’s property and casualty side, and the same team that handles your home and auto coverage. One agency, one set of people who know your situation.
About the RICP® designation
The Retirement Income Certified Professional designation is conferred by The American College of Financial Services, an accredited institution. It requires graduate-level coursework, examination, ongoing continuing education, and adherence to the College’s code of ethics.
Two different questions, thirty years apart
The question that matters while you’re saving is not the question that matters once you start spending. Most plans are built to answer the first one.
While you’re saving: return on your money
What did it earn this year? Growth is the whole job. A bad year is uncomfortable, but you have time and you’re still contributing, so the account recovers.
Once you’re drawing: return of your money
How much can you take, and for how long, before it’s gone? Now a bad year costs you twice — the loss itself, and the shares you had to sell at the bottom to pay yourself.
Making that turn well is most of what we do. More on how retirement income works →
How a conversation actually goes
No cost, no obligation, and no pressure to decide anything in the first meeting.
1
We talk before we recommend
What you’ve saved, where it sits, when you want to stop working, what you’re worried about, and who depends on you. Nothing gets recommended in a first conversation.
2
We put the current picture on paper
Existing policies, income sources, and where the gaps are. Often this step alone changes what people thought they needed.
3
We compare options side by side
If a product fits, you see carrier illustrations with guaranteed and non-guaranteed values shown together — and we explain the difference between them before anything gets signed.
4
You decide, on your timeline
Take the paperwork home. Talk to your spouse, your accountant, your kids. We’ll still be here.
5
We review it each year
Policies are reviewed annually alongside the rest of your coverage, because circumstances change and so do contracts.
Schedule a conversation
Tell us a little about your situation and we’ll get back to you within one business day. There’s no cost and no obligation.
Questions people ask
What does it cost to meet with you?
Nothing. We’re compensated by the insurance carriers when someone purchases a policy, not by the hour. There is no fee for a conversation, a review of your existing policies, or a comparison of options.
Are you financial advisors?
No. We’re licensed insurance producers. We recommend and place insurance products — annuities, life insurance, long-term care and disability income coverage — and we explain how those fit with the rest of your retirement picture. We don’t sell securities, manage investments, or provide investment advisory services. When something falls outside what we do, we’ll say so and point you toward someone who handles it.
Is this a separate company from Browning Insurance Agency?
No. Browning Life and Retirement Solutions is a trade name of Browning Insurance Agency, LLC — the same agency, same license, same team. The separate name reflects a specialty focus, not a separate business.
Do I have to move my home and auto insurance to work with you?
Not at all. Plenty of people work with us on one side and not the other. If you’d like us to look at both, we’re happy to, but it’s never a condition.
What does “guaranteed” actually mean on an annuity?
Guarantees in an annuity or life insurance contract are backed by the financial strength and claims-paying ability of the issuing insurance company — not by any government agency or by our agency. Any values shown that aren’t guaranteed are hypothetical and depend on future conditions that nobody can predict. We show you both columns, every time, so you can see the difference.
Which companies do you represent?
We’re independent and compare contracts across multiple carriers rather than representing a single company. Which carriers are available for a given product depends on the product and your situation — we’ll tell you what we’re comparing and why.
 Browning Life and Retirement Solutions
